
Days after the G7 opened its reserves, the chief executive of Saudi Aramco, Amin Nasser, offered the other half of the picture. Global oil stockpiles, he said, are scarily thin, and rebuilding them could take something on the order of two years. Coming from the man who runs the single largest conventional producer on earth, that is not a market opinion. It is an inventory report from the party best positioned to count.
The two statements are not in contradiction, which is what makes them worth reading together. A reserve release is a demand-side answer to a supply problem: consuming nations lend themselves barrels to break a speculative spike. Nasser’s warning is a supply-side observation about the depth of the pool those loans are drawn from. Commercial and strategic inventories across the system are the shock absorber between a disrupted cargo and a closed refinery, and after a prolonged conflict that has interfered with flows through the Gulf, that absorber has been compressed. Middle East exports have in places recovered to above pre-war levels, which sounds like good news until you notice that stockpiles have not refilled behind them. Flow restored is not buffer restored. Running at full output with empty tanks is a business model with no tolerance for a bad week.
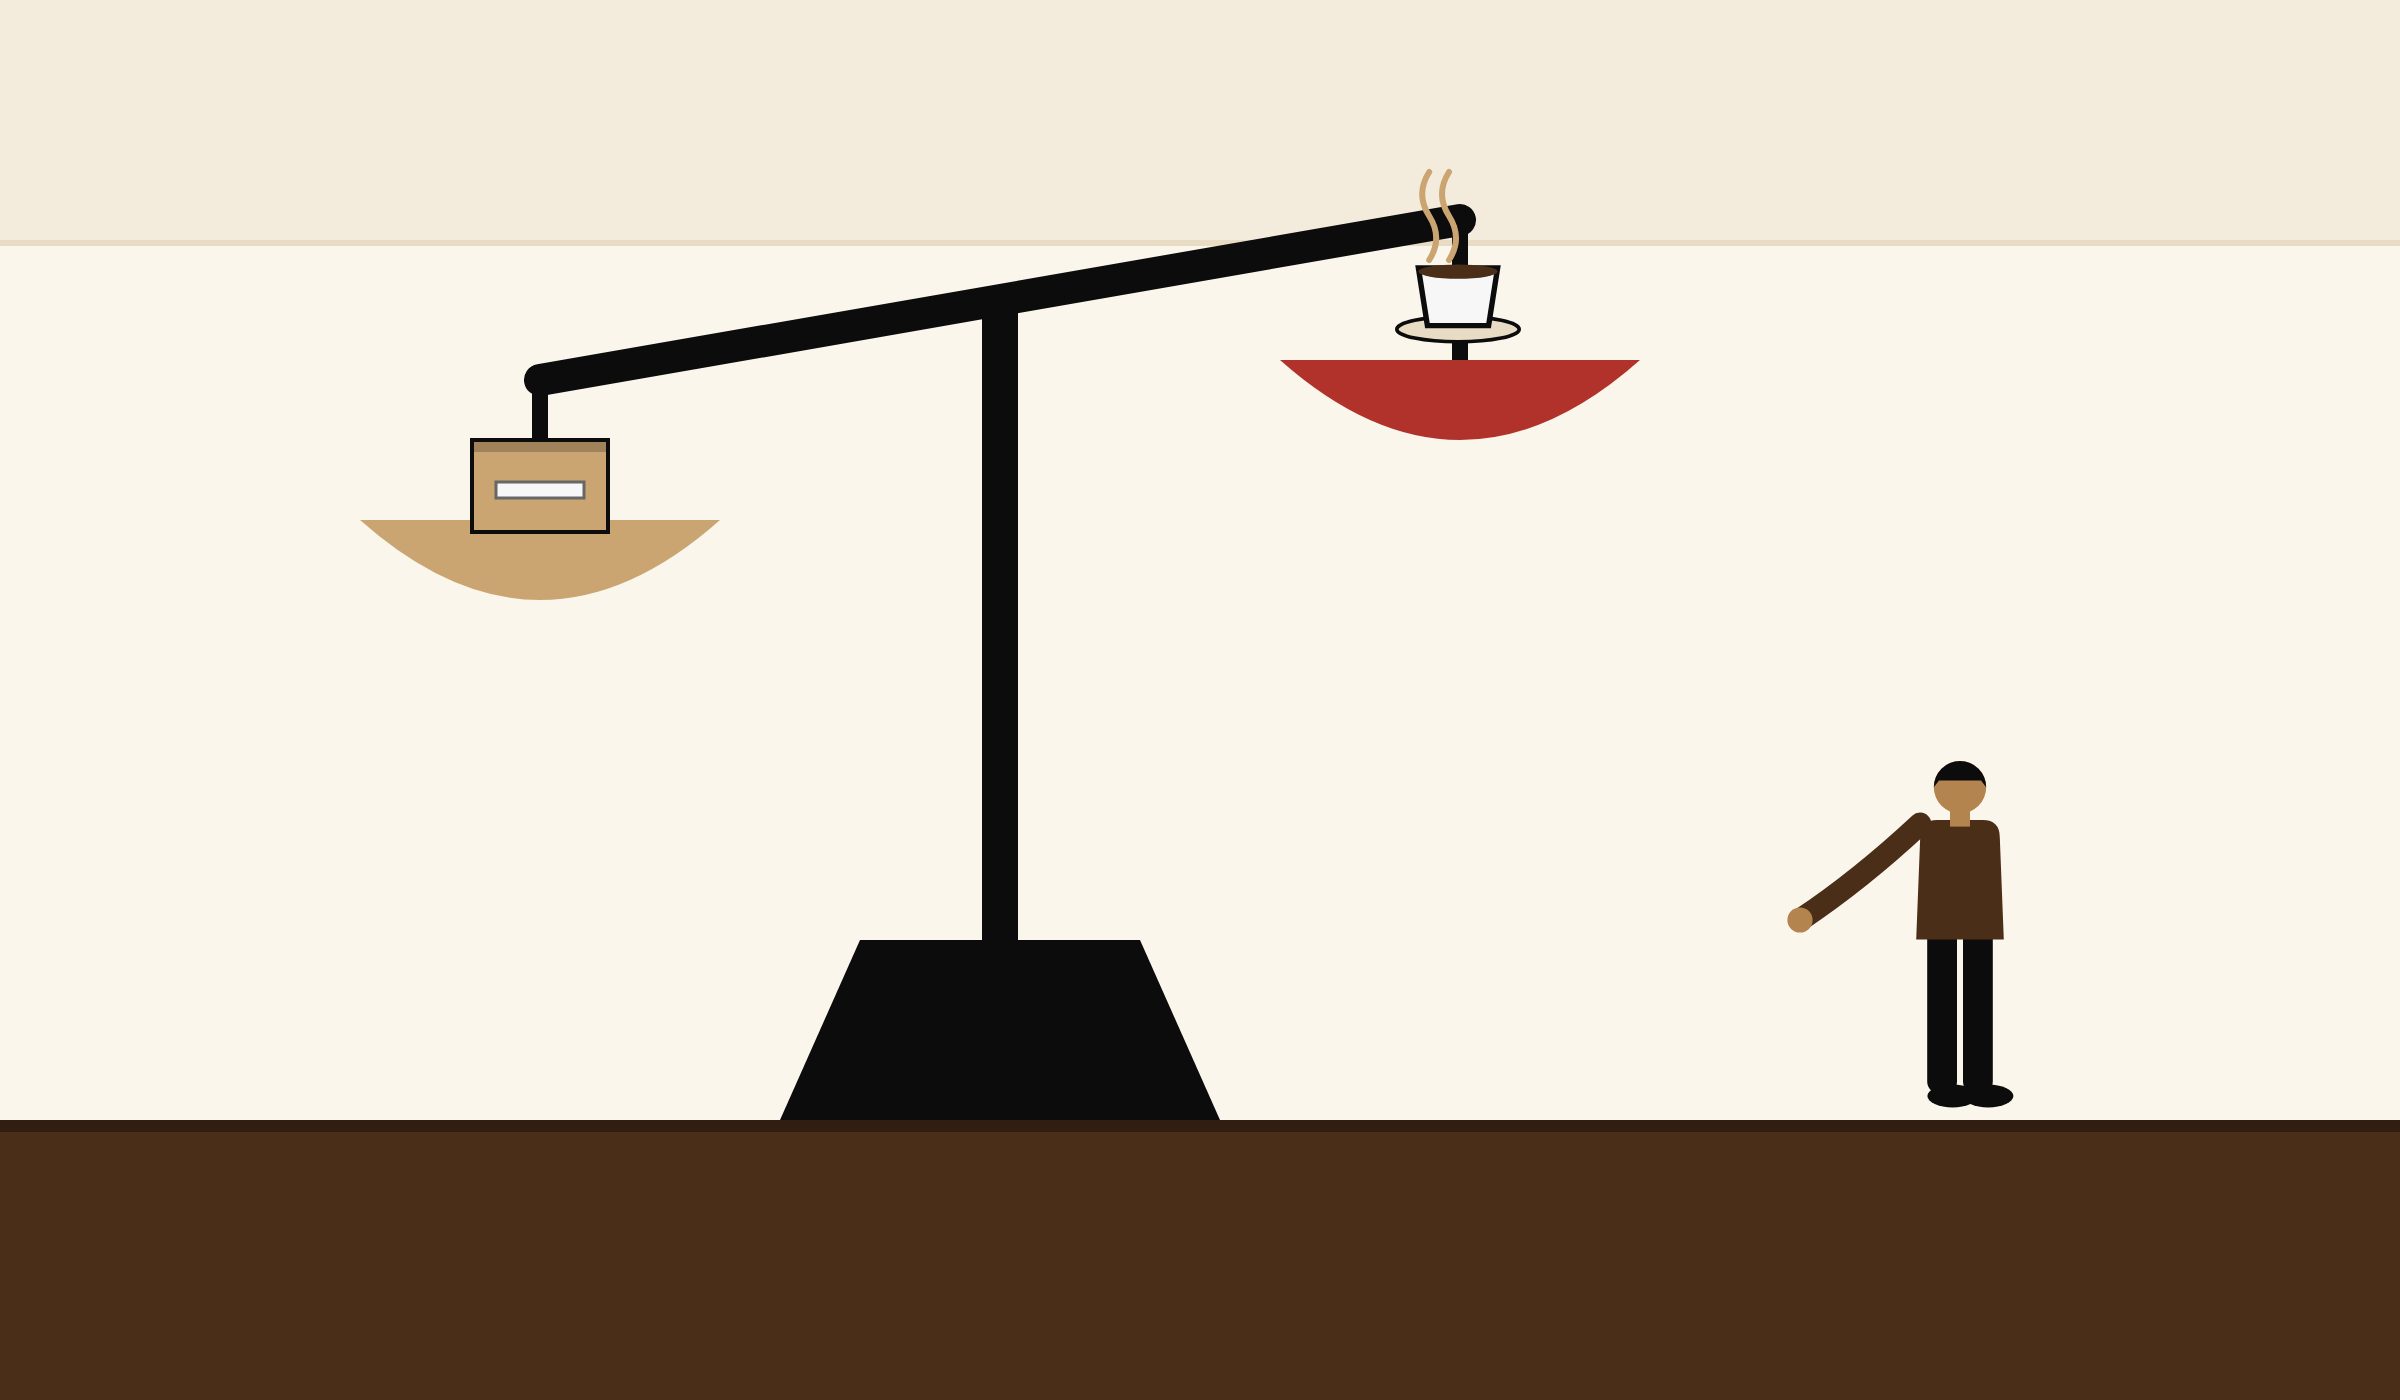
Every café has lived the distinction. There is a difference between a shop that sells 400 cups a day with three weeks of roasted beans resting in the back, and a shop that sells 400 cups a day and takes delivery every morning at five. On any normal Tuesday the two are indistinguishable to the customer. The coffee is the same, the queue is the same, the till rings identically. They are entirely different businesses the moment a lorry breaks down. One has a dull morning. The other has no product, an empty hopper, and a board outside apologising. Resilience is invisible in good weather, which is why it is the first thing cut and the last thing noticed.
The insight is that inventory depth, not headline production, is the variable that determines how violently a market reacts to the next piece of bad news. Price volatility is inversely proportional to buffer. With deep stocks, a tanker attack is an operational nuisance absorbed by storage and the forward curve barely twitches. With thin stocks, the same event is an existential question about physical delivery and the curve snaps into steep backwardation, because the market is no longer pricing oil in three months, it is bidding for oil this week. Everything about the recent price behaviour, the four percent sessions and the wide Brent premium over US crude, is consistent with a market that knows the buffer is shallow and is pricing accordingly.
A two-year rebuild horizon also carries a harder implication. Refilling stocks requires sustained production above consumption, which means someone has to produce barrels that nobody immediately burns and carry the cost of storing them. That only happens when the price structure pays for it, which generally means a market in contango, which generally means a market that has already stopped being frightened. The sequence is therefore uncomfortable: the buffer cannot be rebuilt until calm returns, and calm is harder to establish while the buffer is thin. That loop is the single most important structural fact in the oil complex right now, and the man who said it out loud has more barrels under management than anyone else in the conversation.
So the tanks are low, the output is high, and the system is running without a spare. The espresso is still excellent. There is simply nothing behind it.
Source: TheStreet, “Aramco CEO warns global oil stockpiles are ‘scarily thin'”
